Better’s Bitcoin-Backed Mortgages Lock Borrower Collateral Until Full Repayment
Better Mortgage’s bitcoin-backed home loans, built with Coinbase, hold pledged BTC in custody for the full loan term — raising custody questions as crypto-collateralized mortgages go mainstream.

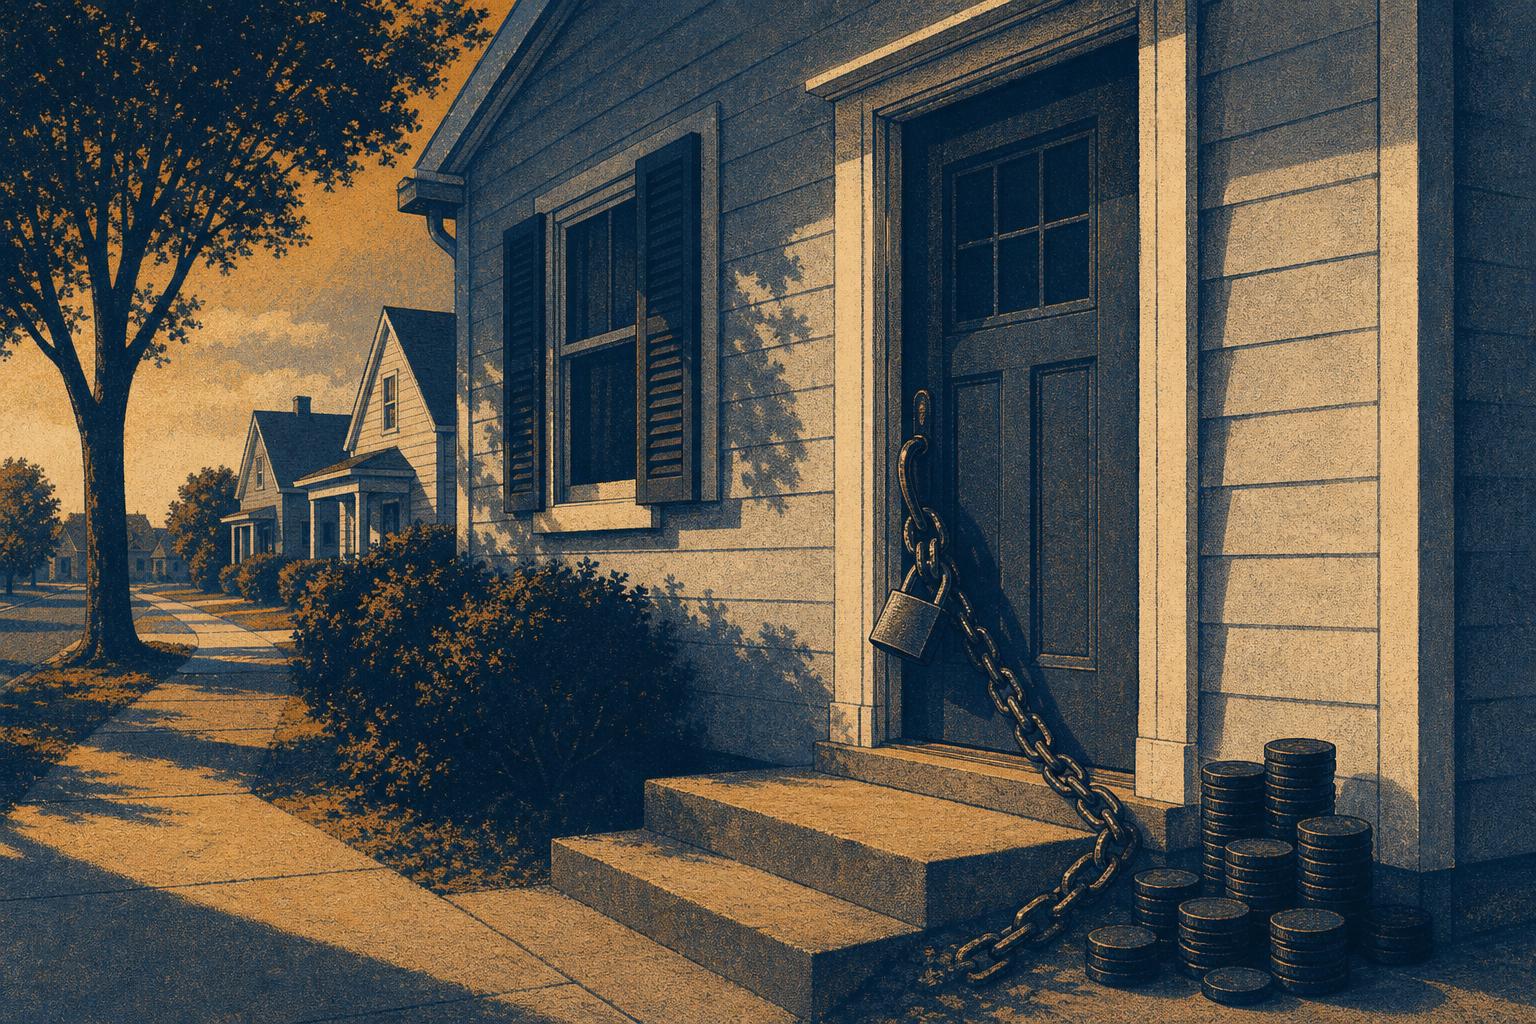
Better Mortgage and Coinbase hold a borrower’s pledged cryptocurrency for the full life of the mortgage. The collateral comes back only after the loan is repaid or refinanced. That custody arrangement, CoinDesk reported, also permits the lender to reuse the pledged assets. The detail puts rehypothecation risk squarely on the table as crypto-collateralized mortgages move toward the mainstream.
Independent verification of the reuse mechanics was not possible. The CoinDesk article returned HTTP errors across multiple fetch attempts. What Better’s own product page does confirm is the borrower-side restriction. Pledged bitcoin (BTC) or USD Coin (USDC) sits in a Better Mortgage custodial account on the Coinbase platform for the duration of the loan. Better returns 100% of the pledged crypto only once the mortgage is fully repaid or refinanced.
On a 30-year mortgage, a borrower who pledges BTC today could wait until 2056 to get it back.
The structure is not simple. According to National Mortgage Professional, the digital asset pledge backs a separate, privately financed loan that funds the down payment. The primary mortgage stays within Fannie Mae conforming-loan parameters. Better originates and services both loans. Coinbase powers the crypto side.
That two-loan architecture matters. The collateral secures the down-payment loan, not the agency mortgage. If Better can reuse it, lending or staking the pledged crypto against other obligations while it sits in custody, borrowers carry exposure they may not fully price in. A segregated-custody model, where pledged assets sit untouched, carries no such risk.
Better did not immediately respond to a request for comment on the reuse term.
The fetched sources describe a product built to reduce friction. No margin calls. No top-ups if bitcoin drops. Mortgage terms stay fixed. Liquidation triggers only after a 60-day payment delinquency, the same threshold that applies to conventional conforming mortgages. USDC pledges earn rewards that can offset mortgage payments and lower the net effective interest rate.
Coinbase One members who close a token-backed or regular mortgage through Better get a rebate worth 1% of the mortgage value, capped at $10,000. An $800,000 loan yields an $8,000 rebate. Better pays it.
The partnership has a demographic in mind. Roughly 52 million American adults, about 20% of the adult population, have owned digital assets, according to market data cited in the product announcement. A 2025 Redfin survey found that 12.7% of Gen Z and Millennial homebuyers sold crypto to fund a down payment, compared with 3.5% of Gen X and 0.5% of baby boomers. Pledging crypto instead of selling it avoids a taxable event. Tax reporting remains the borrower’s responsibility.
Better and Coinbase plan to expand eligible collateral beyond BTC and USDC. Tokenized equities, fixed income, and other tokenized real estate assets are on the roadmap. Coinbase’s custody architecture lets consumers pledge specific quantities and types of tokens rather than an entire account balance.
Vishal Garg, CEO and founder of Better, said the partnership “introduces a new pathway to realizing the American Dream for the 52 million Americans who own digital assets.” Max Branzburg, head of consumer and business products at Coinbase, said the ability to “transform digital wealth into housing access is an exciting milestone in our mission to increase economic freedom.”
Neither executive addressed the collateral-reuse term in statements reviewed by this outlet. Better’s Tinman AI platform has funded more than $110 billion in loan volume since 2016. The company trades on NASDAQ as BETR. Coinbase trades as COIN.
The custody question is not academic. A borrower who pledges BTC at $60,000 today against a down payment on a $500,000 home is betting the asset’s value over 30 years justifies locking it in a custodial account the lender controls. If that lender can deploy the pledged BTC elsewhere, earning yield or backing other loans or posting it as its own collateral, the borrower’s risk profile changes. Nothing on the mortgage disclosure form would reflect it.
Traders, as ever, disagree on whether the trade is worth it.